Withholding Tax on Interest to be Replaced by Paying Agent Tax System

•

Share on:

The Swiss Federal Council issued a proposal on 17 December 2014 to replace the current withholding tax on interest payments by a new paying agent tax system. The new system would be applicable to both domestic and foreign issued bonds and debentures. A Swiss paying agent would have to withhold the Swiss withholding tax, if  the payment would be made to a domestic individual. Payments to domestic entities as well as payments to foreign persons would be out of scope of the Swiss withholding  tax system.

By Stefan Oesterhelt (Reference: CapLaw-2015-5)

1) Current law

Under the current law interest paid by a Swiss resident borrower is not in principle subject to Swiss withholding tax (Verrechnungssteuer) of 35%, unless the instrument under which interest is paid is classified as a “bond” (Anleihensobligation), a “debenture” (Kassenobligation) or a “deposit” (Kundenguthaben) for Swiss withholding tax purposes.

The Swiss withholding tax has to be paid by the issuer of such bond, debenture or deposit to the Swiss Federal Tax Administration. The bondholder or creditor has the possibility to reclaim the Swiss withholding tax based on internal law (if it is a Swiss resident person) or based on a double taxation treaty.

The interest component of structured products issued by a domestic entity as well as retained profits and distributions of domestic mutual funds (unless they derive from capital gains) are also subject to 35% Swiss withholding tax.

2) The Proposal of 17 December 2014

The new withholding tax law proposed by the Swiss federal council on 17 December 2014 will replace the current withholding obligation of the issuer (or the Swiss guarantor, as the case may be) for a withholding obligation of Swiss paying agents. Swiss paying agents will have to remit 35% withholding tax to the Swiss federal tax administration if the interest is paid to a Swiss resident individual in the following cases:

  • Bonds and debentures issued by a Swiss or foreign resident entity (irrespective whether the proceeds of a foreign issued bond will be used in Switzerland or not);

  • Interest component of structured products issued by Swiss or foreign resident entity;

  • Interest component of distributions and retained profits by Swiss and foreign mutual funds;

  • Interest payments on bank deposits.

The new paying agent tax will also apply to bonds which are currently exempt from Swiss withholding tax such as CoCo-Bonds and Write-Down-Bonds.

No distinction will be made between Swiss and foreign issued bonds, debentures, structured products and mutual funds.

3) Function of Swiss Paying Agent

The paying agent, i.e., any person who within the conduct of its business regularly or occasionally remits, transfers or credits interest in connection with bonds and debentures (as defined), or collects such interest for third parties, will be responsible for determination whether a payment constitutes a taxable interest payment and be liable for the tax to be deducted, in the worst case for the grossed-up tax amount. In addition, the paying agent will have to deduct withholding tax on the accrued interest also in the case of a sale of such bond. This is fundamentally new, as accrued interest components are currently generally not subject to the withholding tax.

The paying agent will also be responsible for determining whether the exemption for foreign investors applies, i.e., whether the beneficial owner is resident outside Switzerland. If the paying agent has any doubt about the identity of the beneficial owner he will be required to withhold.

Accordingly, the tasks of Swiss paying agents are sensible and demanding. If the Swiss federal tax administration in an audit concludes that the Swiss paying agent did not withhold tax as required, the paying agent will be liable for tax not withheld, as mentioned earlier, in the worst case on the grossed-up amount.

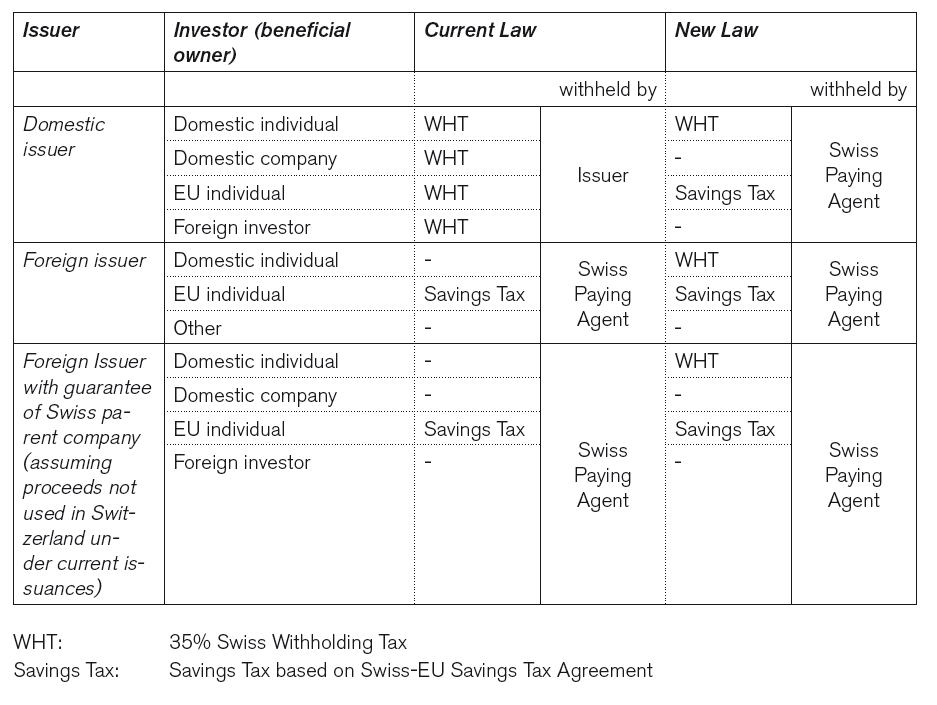
4) Comparison of Current Law and Proposed New Law

The diagram below compares the basic Swiss withholding tax situation under the current and the new law and includes the EU Savings Tax:
CapLaw-2015-5

Stefan Oesterhelt (stefan.oesterhelt@homburger.ch)

Discover more articles

We provide up-to-date information on legal and regulatory developments regarding the capital markets, publish concise articles on developments in the Swiss and international financial markets, and announce recent deals and forthcoming events.

  • FinSA Conduct Obligations: FINMA‘sRecent Enforcement Activity

    FINMA has intensified its enforcement of the conduct obligations governing individual financial services under the Financial Services Act (FinSA). The publicly communicated conclusions of two recent enforcement proceedings are good examples of interventions by the regulator under the FinSA conduct regime. Accompanied by FINMA Guidance 03/2026, which highlights recurring risk patterns, these cases signal that the conduct obligations are now firmly on FINMA‘s enforcement radar.


  • KAPITALMARKTRECHT IM FOKUS 2026 – CONFERENCE REPORT | 19 August 2026, SIX ConventionPoint, Zurich

    On 19 August 2026, practitioners, academics and market participants convened at SIX ConventionPoint in Zurich for Kapitalmarktrecht im Fokus 2026. Under the Title “Clarity or Room for Interpretation? Challenges in Interpreting Bond Terms and Conditions“ (Klarheit oder Auslegungsspielraum? Herausforderungen bei der Interpretation von Anleihensbedingungen), the conference examined how standardized bond terms should be interpreted, the interaction between contractual provisions and regulatory requirements and the significance of prospectuses, risk factors and changing market practice. Particular attention was paid to regulatory capital instruments and the Point of Non-Viability (PONV), against the background of the write-down of Credit Suisse AT1 instruments and the…


  • EHRA CLARIFIES REGISTRATION PRACTICE FOR CONDITIONAL CAPITAL WITHIN AND OUTSIDE THE CAPITAL BAND 

    In a practice note dated 27 August 2026, the Federal Commercial Register Office (EHRA) clarified the registration practice applicable where a company‘s articles of association provide for conditional capital both within a capital band and outside the capital band. This article sets out the resulting registration practice.


  • Swiss advisers subject to the Swiss Anti-Money Laundering Act: Scope and Duties

    Effective 1 October 2026, the revised Swiss Anti-Money Laundering Act will extend Switzerland‘s anti-money laundering framework to advisers participating professionally in covered transactions. Lawyers, notaries, fiduciaries, accountants, tax advisers, M&A advisers and other professionals may become subject to due-diligence, organizational and certain reporting requirements under the AML framework even if they do not execute financial transactions themselves. This article summarizes the new regime, its principal exemptions and its consequences for professional advisers.


  • The Impact of Article 21c CRD VI on Swiss Banks‘ Loan Portfolios

    Effective as of 11 January 2027, CRD VI introduces an EU-wide restriction on third-country institutions‘ cross-border lending activities. Under the new article 21c CRD VI, Swiss banks may no longer extend loans, provide guarantees, or make credit commitments to EU-domiciled borrowers without an authorized subsidiary or branch in the relevant member state. The prohibition covers all corporate finance activities with an EU nexus, including syndicated credit facilities.


  • DocMorris Finance B.V.‘s Issuance of CHF 96.8 Million Senior Guaranteed Convertible Bonds Due 2031 and Concurrent Repurchase of Outstanding Convertible Bonds Due 2028

    On 11 September 2026, DocMorris Finance B.V., a directly wholly-owned subsidiary of DocMorris AG (SIX: DOCM), successfully completed the private placement of CHF 96.8 million 1.5 per cent. senior unsecured convertible bonds due 16 March 2031, unconditionally and irrevocably guaranteed by DocMorris AG and convertible into existing and/or newly issued registered shares of DocMorris AG. Concurrently with the new issuance, DocMorris AG completed the full repurchase of its outstanding 3.0 per cent. convertible bonds due August 2028 with a nominal amount of CHF 49.6 million through privately negotiated bilateral transactions. The repurchased bonds will be cancelled. The transaction reduced the…